Path
At a glance
Contents
Written on 2026-10-26 after checking public pages of the FSC, KINFA, the Ministry of Health and Welfare, Gov24 and Bokjiro. This is not a recommendation of any product. No account was opened and no logged-in screens were viewed. Terms and dates change, so check the official site for current status before applying. Nothing here promises income.
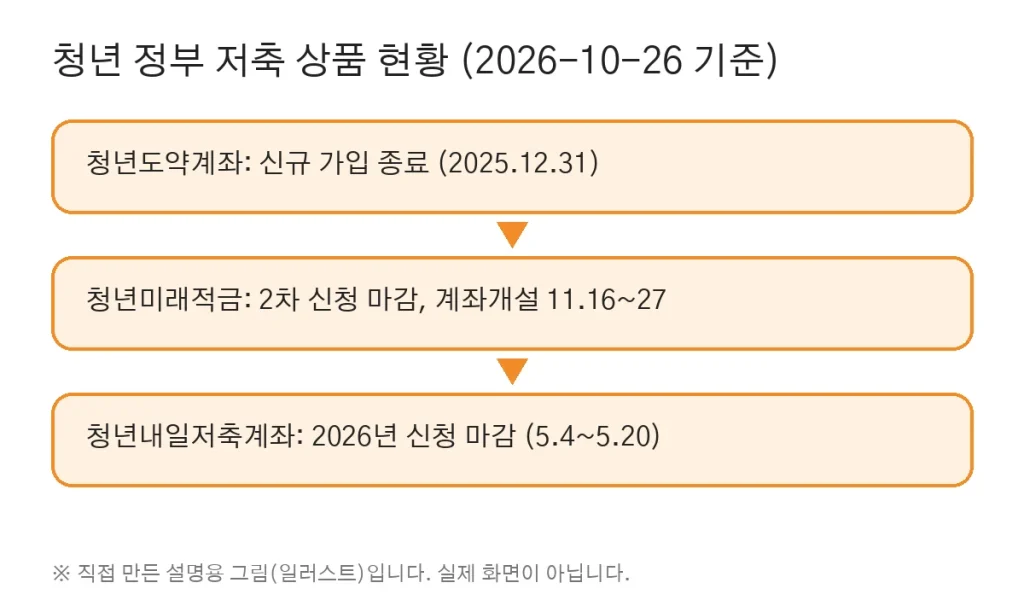
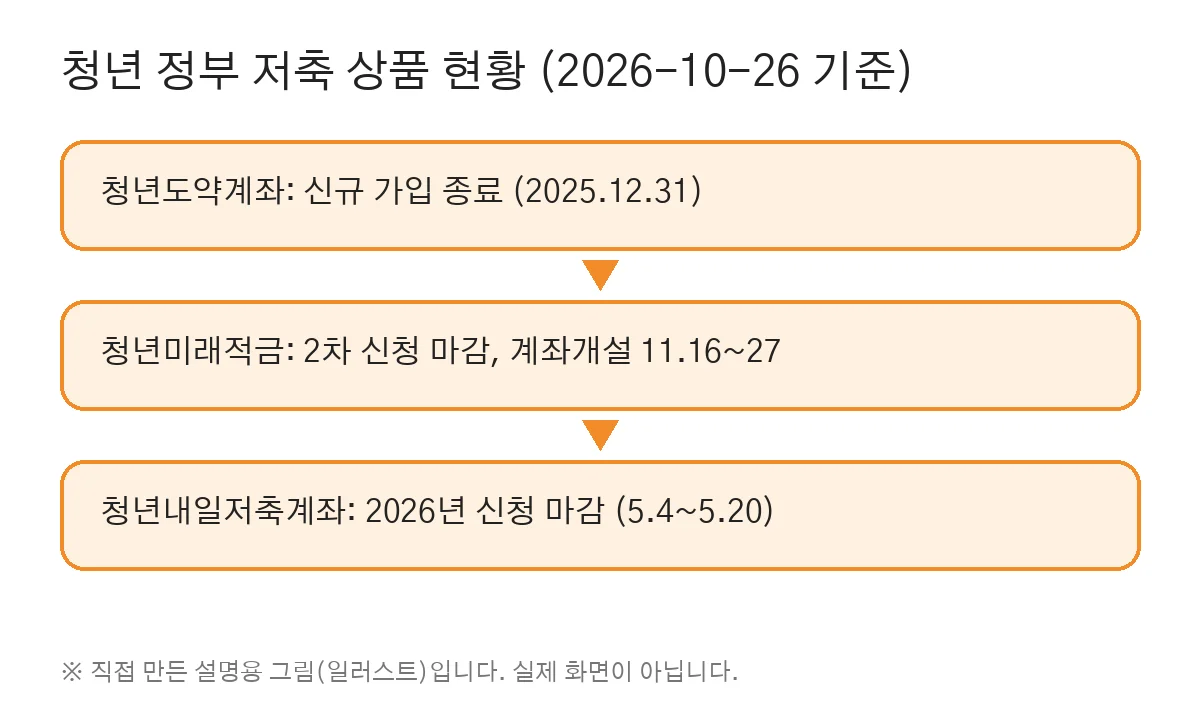
The diagram below is a self-made illustration, not a real screen.
The government adds money to young people’s savings through a few plans with similar names.
This guide sums up the official notices as of 2026-10-26. It doesn’t recommend any plan. Use it to check whether you qualify.
Who this is for
- Workers or small business owners aged 19–34
- Working young people aged 15–39 in low-income households
- Anyone wondering whether the Youth Leap Account is still open
1. Youth Leap Account (청년도약계좌, KINFA): closed to new sign-ups
- KINFA’s official page lists it as a discontinued product. New sign-ups closed on December 31, 2025.
- Existing account holders keep the government contribution and tax-free interest until the account matures (5 years).
- Terms (for existing holders):
- 5-year term, deposit up to ₩700,000 a month
- Government contribution of up to ₩33,000 a month
- Interest income is tax-free
2. Youth Future Savings (청년미래적금, FSC/KINFA)
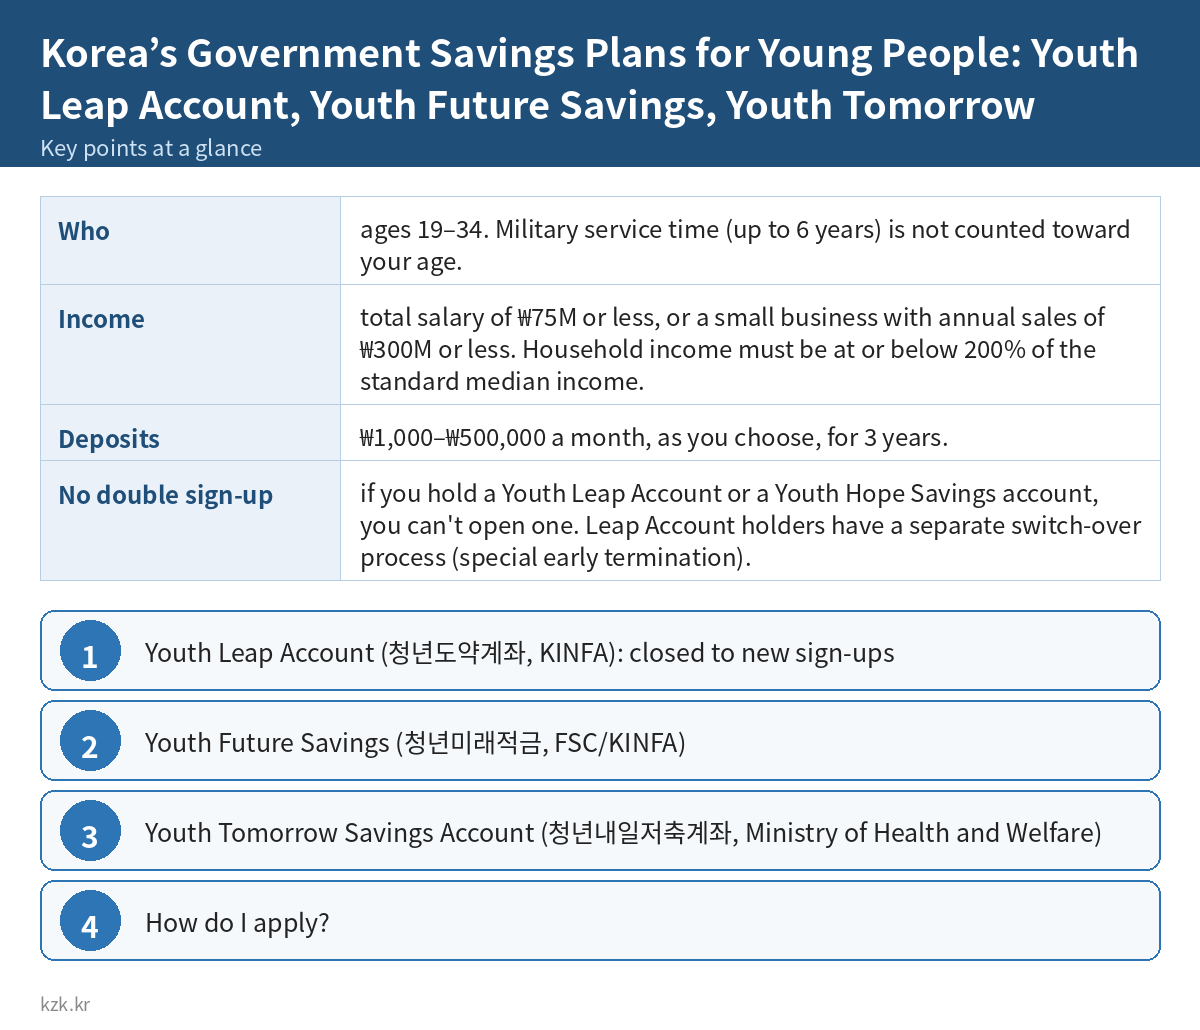
- Who: ages 19–34. Military service time (up to 6 years) is not counted toward your age.
- Income: total salary of ₩75M or less, or a small business with annual sales of ₩300M or less. Household income must be at or below 200% of the standard median income.
- Deposits: ₩1,000–₩500,000 a month, as you choose, for 3 years.
- Government contribution: a percentage of what you deposit each month.
- Standard type: 6% (up to ₩30,000 a month)
- Preferential type: 12% (up to ₩60,000 a month)
- Your type depends on your income, whether you work at an SME, and similar factors.
-
Salaried applicants earning over ₩60M and up to ₩75M get no contribution, only the tax exemption.
-
Tax: interest income is tax-free.
- No double sign-up: if you hold a Youth Leap Account or a Youth Hope Savings account, you can’t open one. Leap Account holders have a separate switch-over process (special early termination).
- Round 2 schedule: applications ran October 7–16 and are now closed. If you passed screening, you must open the account in the provider’s app between November 16 and 27. You can’t open it after that.
- Interest rates differ by provider. You can compare them on the Korea Federation of Banks consumer portal.
3. Youth Tomorrow Savings Account (청년내일저축계좌, Ministry of Health and Welfare)
- Who: ages 15–39, earning at least ₩100,000 a month from work or a business. Household recognized income must be at or below 50% of the standard median income.
- Support: save at least ₩100,000 a month and the government adds ₩300,000 a month.
- To receive the money, you must do all of these over 3 years:
- Keep the account open
- Keep working
- Complete the required training
-
Submit a plan for how you’ll use the money
-
2026 intake: applications ran May 4–20 through Bokjiro or a community center. They are now closed.
- From 2026, the plan focuses on households at or below 50% of the standard median income (Ministry announcement).
How do I apply?
- Youth Future Savings: apply and open the account after logging in to a participating bank’s app.
- Youth Tomorrow Savings: apply online after logging in to Bokjiro, or visit a community center.
- This guide doesn’t describe the screens you see after logging in. Follow each agency’s official instructions.
Common mistakes
- Thinking you can still open a new Youth Leap Account
- Passing screening but missing the account-opening window (Nov 16–27)
- Assuming you can hold both a Leap Account and Future Savings
- Guessing your contribution rate without checking the preferential-type conditions
Checklist
- ☐ Does your age fit? (Subtract military service time.)
- ☐ Did you check both the personal and household income limits?
- ☐ Do you already hold a government savings plan? (Double sign-ups aren’t allowed.)
- ☐ Did you check the next intake and account-opening dates on the official page?
- ☐ Did you read the conditions you must keep until maturity?
For more money you may be missing, see our guide to finding hidden money.
We also have a $4.99 PDF guide that collects more everyday money-saving tips. Take a look if it’s useful →
FAQ
Is Korea’s Government Savings Plans for Young People: Youth Leap Account, Youth Future Savings, Youth Tomorrow Savings a legit way to make money?
Yes, it is legal and used worldwide. Written on 2026-10-26 after checking public pages of the FSC, KINFA, the Ministry of Health and Welfare, Gov24 and Bokjiro. This is not a recommendation of any product. No account was opened and no logged-in screens were viewed. Terms and dates change, so check the official site for current status before applying. Nothing here promises income. Results depend on your time, skills and consistency; never pay upfront fees to unknown "opportunities".
What are the main pros and cons of Korea’s Government Savings Plans for Young People: Youth Leap Account, Youth Future Savings, Youth Tomorrow Savings?
Pros: Workers or small business owners aged 19–34, Working young people aged 15–39 in low-income households, Anyone wondering whether the Youth Leap Account is still open. Cons: KINFA's official page lists it as a discontinued product. New sign-ups closed on December 31, 2025., Existing account holders keep the government contribution and tax-free interest until the account matures (5 years)., Terms (for existing holders):, 5-year term, deposit up to ₩700,000 a month, Government contribution of up to ₩33,000 a month, Interest income is tax-free.
How do I start Korea’s Government Savings Plans for Young People: Youth Leap Account, Youth Future Savings, Youth Tomorrow Savings step by step?
The full step-by-step guide is free to read on this page.
🎁 Free: 7-day side-hustle starter checklist
Leave your email and get the free checklist now. No spam, unsubscribe anytime.
Popular guides
- Top 10 Ways to Make Money Starting This Week (Free Checklist)
- How to Make Money as a Student: Legit Ideas (2026)
- Passive Income Ideas: Realistic Options for 2026
- Make Money Online Without Investment: 20 Free Ways
- How to Make Money with AI: 50 Practical Ways (2026)
- How to Make Money From Home: 20 Legit Ways
- Make Money Online for Beginners: 15 Easy Ways to Start
- How to Make Money as a Mom: 16 Flexible Ideas (Work Around Nap Time)
- 16 Legit Ways to Make Money Fast (This Week)
- How to Make Money as a Teenager: 16 Safe Ideas
- 14 Remote Jobs With No Experience Needed
Next method: Received a Mobile Gift Voucher? Who Can Extend It or Get the Refund →