Start cost $0 · First income ~2–5 months
Path
Contents
🧭 At a glance: is this for you?
If you pay income tax in Korea, money you put into a pension savings account (연금저축) or an IRP (individual retirement pension account) comes back as a tax credit at the next year-end settlement. You do not earn new income, but you keep more of your pay: 13.2% or 16.5% of what you deposit, up to KRW 9 million a year combined. Only deposits made by 31 December 2026 count for this year.
- Best for: Salaried workers who do year-end tax settlement, and freelancers or business owners who file income tax in May, with savings they will not need for years
- Startup cost: ₩0 to open (most accounts are free; product fees vary)
- Time to first income: 2–5 months: the credit appears in the February–March payroll after year-end settlement, or after the May filing for freelancers
- Difficulty: Easy: open an account in an app and deposit before year-end
👍 Pros
- A fixed 13.2% or 16.5% credit on what you deposit, set by law
- You can deposit in one lump sum in December
- The money stays yours and keeps growing tax-deferred for retirement
👎 Cons and cautions
- You must keep it until age 55 and take it as a pension to keep the benefit
- Early termination: 16.5% “other income” tax on credited deposits and gains
- No credit if you have little or no income tax to pay
📘 What the full guide below covers: checking your remaining limit, choosing your credit rate, opening accounts, the best deposit order, a worked example, a first-week plan and the mistakes that cancel the benefit.
💰 How much comes back (2026 rules)
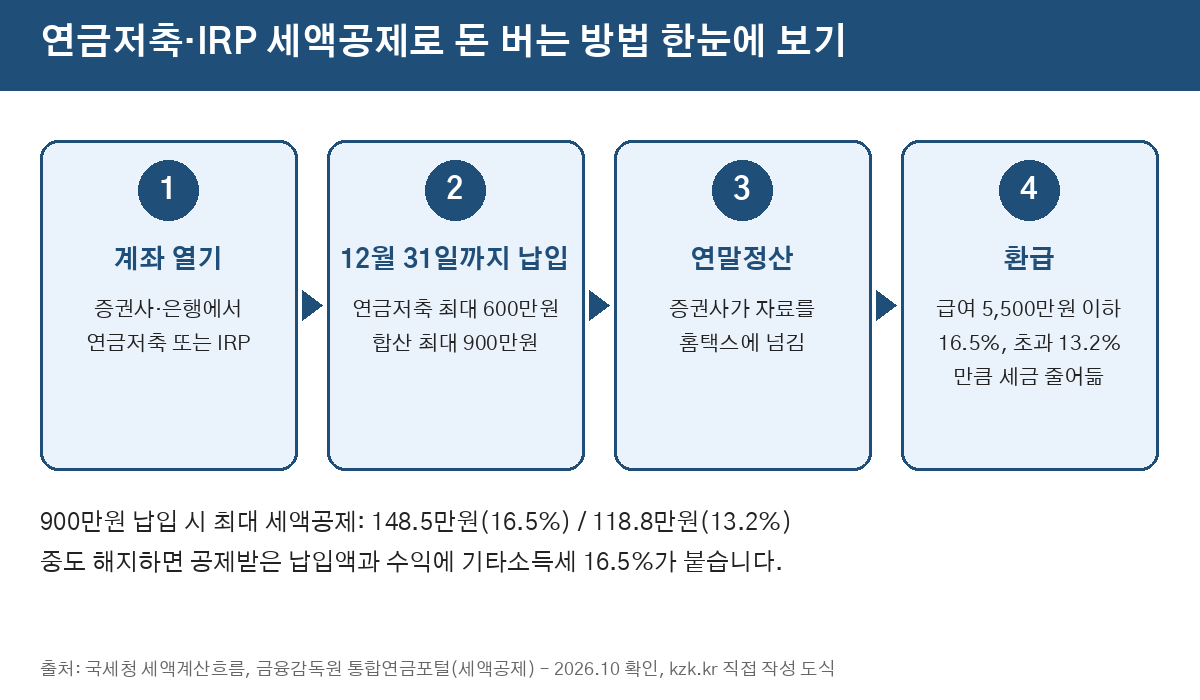
- Total pay ₩55 million or less (earned income only): 16.5% credit → up to ₩1,485,000 on ₩9 million (about $1,076)
- Total pay over ₩55 million: 13.2% credit → up to ₩1,188,000 on ₩9 million (about $861)
- Pension savings alone counts up to ₩6 million; IRP fills the rest up to ₩9 million combined
- Freelancers and business owners use a total income amount of ₩45 million as the dividing line
Figures include local income tax and come from the Income Tax Act (Art. 59-3), the National Tax Service and the Financial Supervisory Service, checked October 2026. You cannot get back more than the tax you owe. General information, not tax or investment advice.
🪜 Basic steps (summary)
- Check how much you have already deposited this year in your pension savings and IRP apps.
- Find your total pay to see whether your rate is 16.5% or 13.2%.
- Open a pension savings account (securities firm) or IRP (bank or securities firm) if you do not have one.
- Deposit the remaining amount before 31 December, ideally by mid-December.
- In January, confirm the deposit shows up in Hometax’s simplified year-end data.
Want a printable overview of more ways to grow your money? Our compares 30 options side by side.
📘 Full practical guide (October 2026)
🪜 Step-by-step
- Check this year’s deposits. In your securities or bank app, open the pension savings and IRP menus and note this year’s deposits. If your company has a DC-type retirement pension, the employer’s contributions do not count; only extra money you add yourself does.
- Find your credit rate. Look at last year’s withholding receipt (근로소득 원천징수영수증) or Hometax’s year-end tax preview. Total pay of ₩55 million or less means 16.5%; above that, 13.2%. Freelancers use total income of ₩45 million as the line.
- Check that you actually owe tax. Your “determined tax” (결정세액) on last year’s receipt shows roughly how much tax there is to reduce. If it is small, depositing the full ₩9 million will not give you the full credit.
- Open the account if needed. Pension savings: in a securities app, choose “open pension savings account” (ID card and a phone in your name). IRP: in a bank or securities app, “open individual IRP”; you need earned or business income. Compare fees on the FSS comparison site before choosing.
- Deposit in the right order. A common order: pension savings up to ₩6 million first, then up to ₩3 million in IRP. Deposits arriving after 31 December count for next year, and banks have year-end cut-off times, so aim for mid-December.
- Decide what the money is invested in. Left alone it stays as cash. Deposits, bond funds or index ETFs are all possible; this is your own decision, and risk products can lose value.
- Confirm at settlement. In January the deposits appear in Hometax’s simplified year-end data. Check the pension account line on your company’s form; freelancers enter the same amount in the May filing.
🧮 Worked example
Total pay ₩40 million, ₩3 million already in pension savings this year:
- Current credit: ₩3,000,000 × 16.5% = ₩495,000
- Add ₩3 million to pension savings + ₩3 million to IRP in December: ₩9,000,000 × 16.5% = ₩1,485,000
- Extra refund: ₩990,000, as long as the determined tax is at least that large
Illustrative numbers; your result depends on your tax and other credits.
🔗 Official sources and tools
- Korean law database — Income Tax Act Article 59-3 (pension account tax credit)
- National Tax Service — year-end settlement guidance, phone 126
- Hometax — year-end tax preview and simplified data
- FSS Finlife — compare pension product fees and returns
- FSS integrated pension portal — see all your pension accounts in one place
📅 First-week plan
- Day 1: Check this year’s pension savings and IRP deposits.
- Day 2: Find your total pay and credit rate.
- Day 3: Check last year’s determined tax.
- Day 4: Open an account if you need one.
- Day 5: Decide the amount, keeping 3–6 months of living costs aside.
- Day 6: Deposit.
- Day 7: Confirm the app shows it as a tax-credit-eligible deposit.
🚫 Common mistakes
- Putting all ₩9 million into pension savings: only ₩6 million counts there.
- Depositing far more than your tax: you cannot get back more than you owe.
- Depositing on 1 January: it counts for the following year.
- Cancelling early: 16.5% other income tax wipes out the benefit. Lower rates apply only for legal reasons such as serious illness; check the FSS guide first.
- Expecting partial withdrawals from IRP: outside legal reasons, IRP usually has to be closed in full.
⚠️ Watch out for scams
Calls or texts offering a “special year-end tax benefit” that ask you to install an app or share a verification code are not from your bank. Open pension accounts yourself in your financial company’s official app. Be wary of anyone promising guaranteed high returns, and ask the FSS (1332) if in doubt.
📚 Related guides
- Missed a Deduction at Year-End Tax Settlement? Claim It Within 5 Years
- Rent tax credit and youth rent support, separately
- Donation Tax Credit in Korea and the Hometown Love Donation (2026 Year-End Tax)
- Korea’s Government Savings Plans for Young People: Youth Leap Account, Youth Future Savings, Youth Tomorrow Savings
- How to Make Money with Index Fund Investing
- How to Make Money Capturing Your Employer Retirement Match
Last updated: October 29, 2026. General information, not tax or investment advice.
Want to run Korea’s Pension Savings and IRP Tax Credit as a 30-day plan? The PDF guide (one-time .99) compares 30 methods with steps and income estimates. All steps above stay free.
See full guide →FAQ
Is How to Make Money with Korea’s Pension Savings and IRP Tax Credit (Check Before Dec 31) a legit way to make money?
Yes, it is legal and used worldwide. If you pay income tax in Korea, money you put into a pension savings account (연금저축) or an IRP (individual retirement pension account) comes back as a tax credit at the next year-end settlement. You do not earn new income, but you keep more of your pay: 13.2% or 16.5% of what you deposit, up to KRW 9 million a year combined. Only deposits made by 31 December 2026 count for this year. Results depend on your time, skills and consistency; never pay upfront fees to unknown "opportunities".
What are the main pros and cons of How to Make Money with Korea’s Pension Savings and IRP Tax Credit (Check Before Dec 31)?
Pros: Best for: Salaried workers who do year-end tax settlement, and freelancers or business owners who file income tax in May, with savings they will not need for years, Startup cost: ₩0 to open (most accounts are free; product fees vary), Time to first income: 2–5 months: the credit appears in the February–March payroll after year-end settlement, or after the May filing for freelancers, Difficulty: Easy: open an account in an app and deposit before year-end. Cons: A fixed 13.2% or 16.5% credit on what you deposit, set by law, You can deposit in one lump sum in December, The money stays yours and keeps growing tax-deferred for retirement.
How do I start How to Make Money with Korea’s Pension Savings and IRP Tax Credit (Check Before Dec 31) step by step?
The full step-by-step guide is free to read on this page.
🎁 Free: 7-day side-hustle starter checklist
Leave your email and get the free checklist now. No spam, unsubscribe anytime.
Popular guides
- Top 10 Ways to Make Money Starting This Week (Free Checklist)
- How to Make Money as a Student: Legit Ideas (2026)
- Passive Income Ideas: Realistic Options for 2026
- Make Money Online Without Investment: 20 Free Ways
- How to Make Money with AI: 50 Practical Ways (2026)
- How to Make Money From Home: 20 Legit Ways
- Make Money Online for Beginners: 15 Easy Ways to Start
- How to Make Money as a Mom: 16 Flexible Ideas (Work Around Nap Time)
- 16 Legit Ways to Make Money Fast (This Week)
- How to Make Money as a Teenager: 16 Safe Ideas
- 14 Remote Jobs With No Experience Needed
Next method: How to Make Money Easier to Track with a Side-Income Ledger Template: Free Excel File + 5 Minutes a Day (2026) →